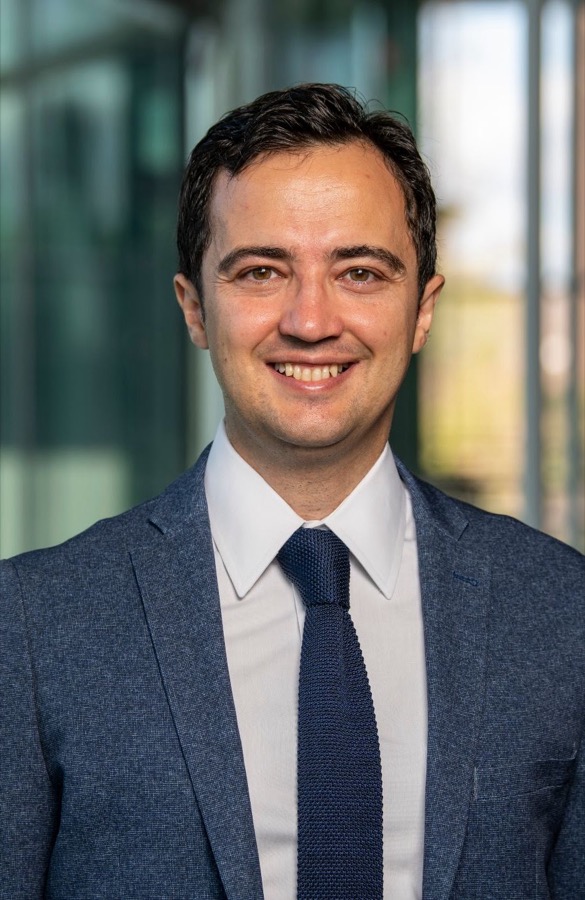
Alp Simsek
Professor of Finance/Yale School of Management
Macroeconomics and finance — asset prices, monetary policy, and speculation.
I am a Professor of Finance at the Yale School of Management. I am also a Research Associate at the National Bureau of Economic Research and a Research Affiliate at the Centre for Economic Policy Research. Previously I was an Assistant Professor of Economics at Harvard University and an Associate Professor of Economics at MIT.
My research, advising, and teaching interests are centered in macroeconomics and finance, and extend into international and behavioral finance. I study the connections between financial markets and the macroeconomy, with an emphasis on understanding the interactions between asset prices and monetary policy. While I am primarily an applied theorist, I also engage with data to test the mechanisms that I emphasize.
I received bachelor's degrees from MIT in 2004, a master's degree from MIT in 2005, and a Ph.D. from MIT in 2010. I was a recipient of the National Science Foundation CAREER award in 2015.
- Co-editor, Journal of the European Economic Association (2024–)
- Associate Editor, Quarterly Journal of Economics (2021–)
- Research Associate, NBER · Research Affiliate, CEPR
Recent working papers
-
Forward Guidance and Financial Conditions
Earlier policy-oriented version: FCI-plot: Central Bank Communication Through Financial Conditions, presented at the 2nd Thomas Laubach Research Conference at the Federal Reserve Board.
Abstract
Forward guidance has recently been contested, most visibly in the United States. We investigate its benefits and costs in a model in which monetary policy reaches the economy through financial conditions. Noisy flows move those conditions, and because the central bank adjusts its interest rate gradually, they open output gaps. Arbitrageurs trade against the noise but do not fully offset it, because they are uncertain about policy. Guidance resolves the central bank's view of future demand, which lowers that uncertainty and recruits the arbitrageurs to absorb more of the noise. But the announcement also moves financial conditions today, even though the level the central bank wants today has not changed. The optimal guidance intensity balances these forces. It rises with the amount of noise, with policy uncertainty, and with the persistence of the central bank's view. We then compare interest rate guidance with financial conditions guidance. A projected interest rate embeds the central bank's view of the risk premium alongside its view of the economy, so for a given communication effort it conveys less. Financial conditions guidance can always attain the optimal guidance intensity, whereas interest rate guidance attains it only when guidance is not particularly valuable. Even when both attain it, interest rate guidance requires more communication effort. How much a central bank must say therefore depends on what it talks about. -
Financial Conditions Targeting
Abstract
Non-fundamental inflows into the stock market loosen financial conditions and raise output, while the policy rate responds gradually. Such financial noise explains up to 20% of the variance of financial conditions and output. These facts motivate a macroeconomic model with noise traders, risk-averse arbitrageurs, and gradual interest rate adjustment. In this model, Financial Conditions Index (FCI) targeting can improve macroeconomic stabilization: the central bank announces its expected FCI as a soft near-term target and adjusts the policy rate to keep conditions near it. This commitment reduces FCI volatility, thereby “recruiting” arbitrageurs to insulate the FCI and aggregate demand from noise. -
Stock Market Wealth and Entrepreneurship
Abstract
We use data on stock portfolios of Norwegian households to show that stock market wealth increases entrepreneurship by relaxing financial constraints. Our research design isolates idiosyncratic variation in household-level stock market returns. An increase in stock market wealth increases the propensity to start a firm, with the response concentrated in households with moderate levels of financial wealth, for whom a 20 percent increase in wealth due to a positive stock return increases the likelihood to start a firm by about 20%, and in years when the aggregate stock market return in Norway is high. We develop a method to study the effect of wealth on firm outcomes that corrects for the bias introduced by selection into entrepreneurship. Higher wealth causally increases firm profitability, an indication that it relaxes would-be entrepreneurs' financial constraints. Consistent with this interpretation, the pass-through from stock wealth into equity in the new firm is one-for-one.
Contact
Address
Yale School of Management
165 Whitney Avenue
New Haven, CT 06511